



Calculate Portfolio Return Standard Deviation for a Date Range in Excel

Question details
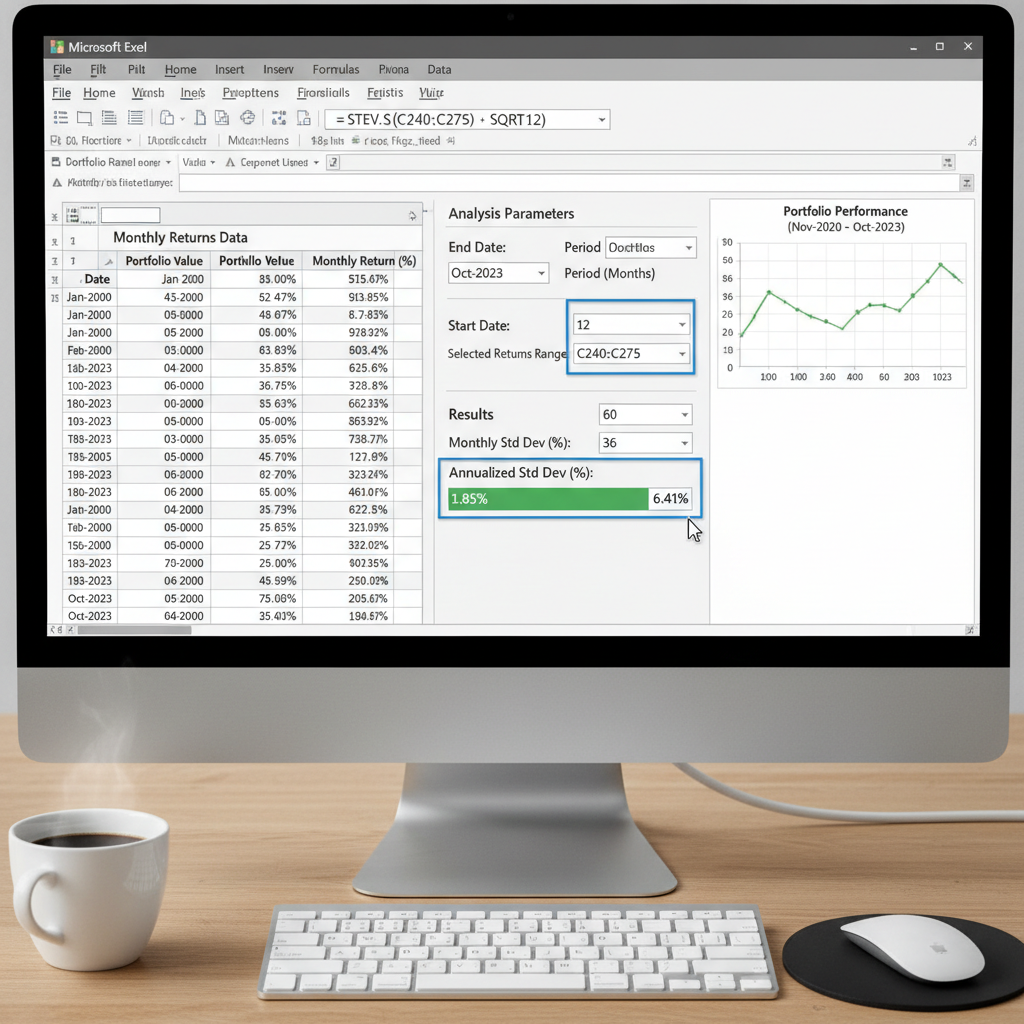
The user needs to calculate the annualized standard deviation of monthly portfolio returns over dynamic historical periods (like 12, 36, 60, or 120 months) before a selected end date.
- Product
- Microsoft Excel
- Device & OS
- not provided
- Scenario
- Performing financial analysis to measure portfolio risk over specific rolling historical date ranges.
- Observed behavior
- Requires a combination of lookup methods to identify the correct date range and statistical formulas to calculate standard deviation, before annualizing the final value.
Ensure your monthly return data is sorted chronologically by date and that your return values are formatted correctly as percentages or decimal numbers.
Use OFFSET, MATCH, and STDEV.P to Calculate Dynamic Standard Deviation
Combine OFFSET and MATCH to dynamically define the date range based on your specified end date and month count, then calculate the annualized standard deviation.
Annualizing standard deviation for monthly data requires calculating the standard deviation of the specific period and then multiplying it by the square root of 12 (SQRT(12)). Using OFFSET and MATCH allows you to dynamically shift and resize the range based on the user-selected end date and the number of months.
Use the MATCH function to find the row number of your chosen end date. For example: =MATCH(TargetDateCell, DateColumnRange, 0).
Use the OFFSET function to select the correct number of previous months. Set the reference to the first cell of your returns, use the MATCH result minus the number of months for the row offset, and set the height to the number of months.
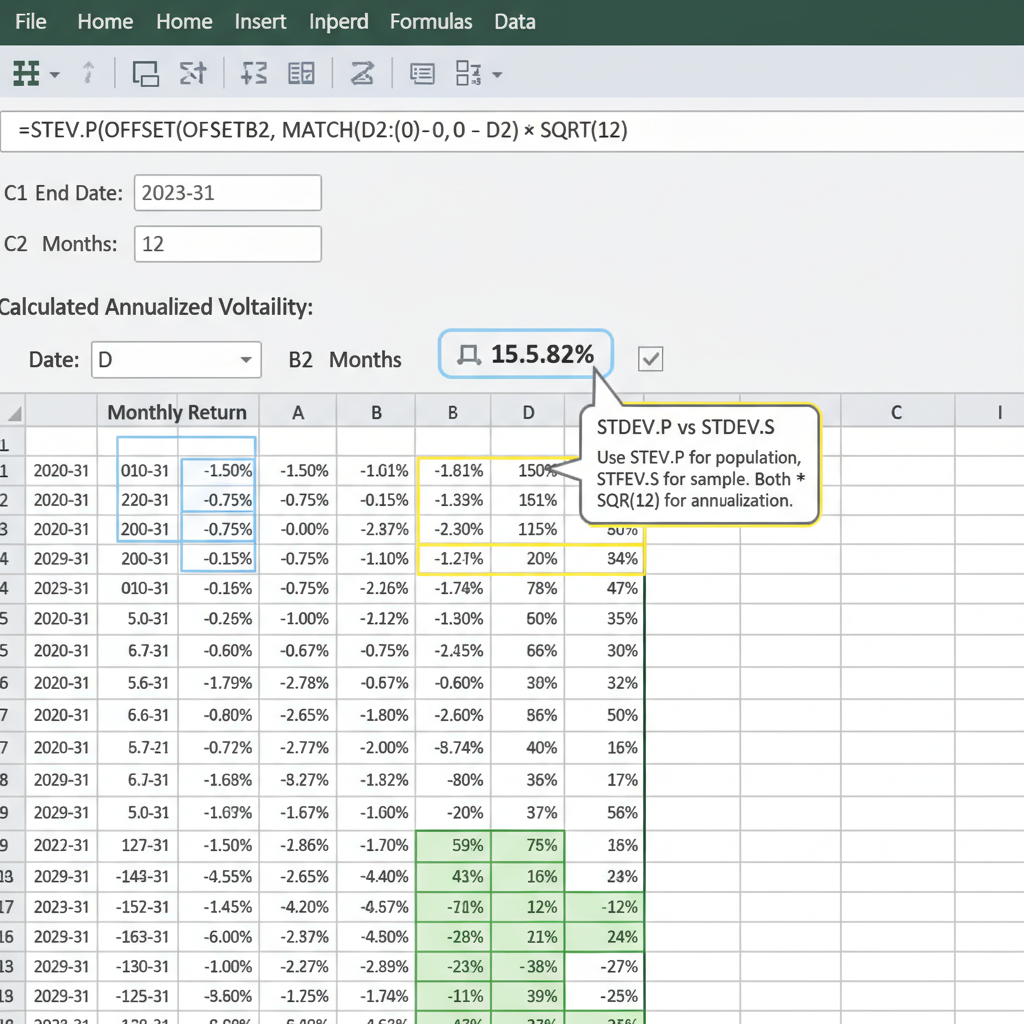
Wrap the OFFSET formula inside the STDEV.P (or STDEV.S) function to calculate the standard deviation for that specific block of returns.
Multiply the entire formula by SQRT(12). The final formula will look similar to: =STDEV.P(OFFSET(ReturnsFirstCell, MATCH(Date, DateRange, 0) - Months, 0, Months)) * SQRT(12).
Calculate Portfolio Risk Dynamically in WPS Spreadsheet
WPS Spreadsheet fully supports advanced statistical functions like STDEV.P, OFFSET, and MATCH, allowing you to build dynamic financial models effortlessly.
- 1. Open Your Data: Launch WPS Spreadsheet and open the workbook containing your historical portfolio returns.
- 2. Select Target Cell: Click the cell where you want the annualized standard deviation result to appear.
- 3. Insert Formula: Navigate to the 'Formulas' tab and click 'Insert Function' to easily search for STDEV.P or STDEV.S.
- 4. Combine with Lookup Functions: Input your dynamic range formula combining OFFSET and MATCH to locate the desired 12, 36, or 60-month range.
- 5. Finalize and Annualize: Multiply the function by *SQRT(12) at the end of the formula bar and press Enter to view the annualized risk metric.
Frequently Asked Questions
Why do I need to multiply by SQRT(12) for monthly returns?
Standard deviation scales with the square root of time. Since there are 12 months in a year, you must multiply the monthly standard deviation by the square root of 12 to properly annualize the risk metric.
How do I change the formula to calculate 36 or 60 months instead of 12?
You can reference a cell containing the number of months (e.g., 36) within the 'height' argument of the OFFSET function. This allows the range to adjust automatically based on your input cell rather than hardcoding the number into the formula.
What happens if the selected end date is not found in the date column?
If the MATCH function cannot find the exact date and is set to exact match (0), it will return an #N/A error. Ensure the lookup value exactly matches the date format in your dataset, or change the match type to 1 or -1 for approximate matches if applicable.


