

Why Excel R-Squared Is Too High When the Intercept Is Zero

Question details
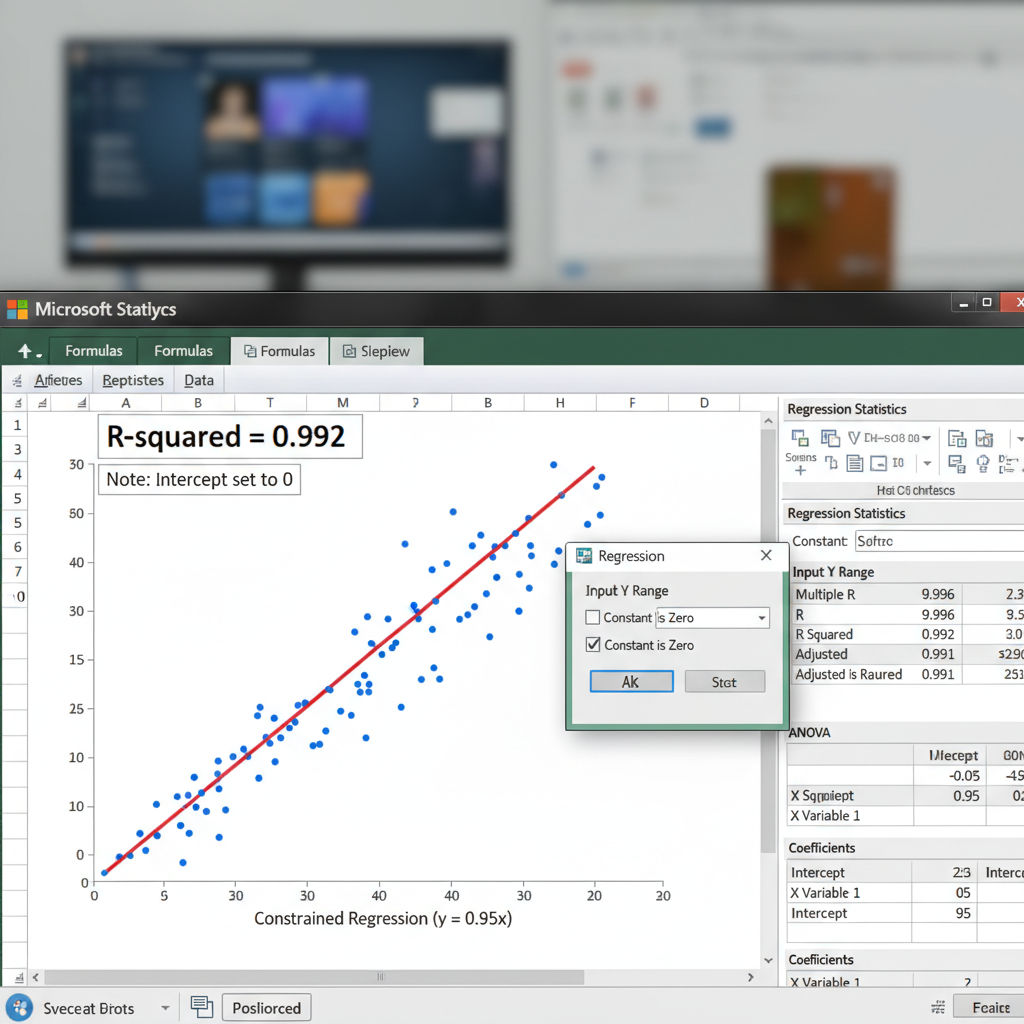
The R-squared value in an Excel linear regression becomes unexpectedly high when the regression line is constrained to pass through the origin.
- Product
- Excel
- Device & OS
- not provided
- Scenario
- Performing linear regression analysis and explicitly setting the intercept to zero.
- Observed behavior
- The R-squared value artificially inflates because forcing a zero-intercept model inherently changes how the total sum of squares is calculated.
Before adjusting your regression model, verify that there is a strict theoretical or physical reason why the dependent variable must exactly equal zero when the independent variable is zero.
Evaluate the Zero-Intercept Model Appropriateness
Understand why the R-squared calculation fundamentally changes and use alternative metrics to determine if the zero-intercept model is statistically valid for your data.
When you force the intercept to zero in Excel, the mathematical formula used to calculate the Total Sum of Squares (TSS) changes. Instead of measuring variance around the mean of your data, it measures variance around zero. This fundamentally shifts the calculation and often artificially inflates the R-squared value.
A higher R-squared in a zero-intercept model does not necessarily mean it represents a better fit than the standard regression model. It simply reflects a different baseline for comparison.
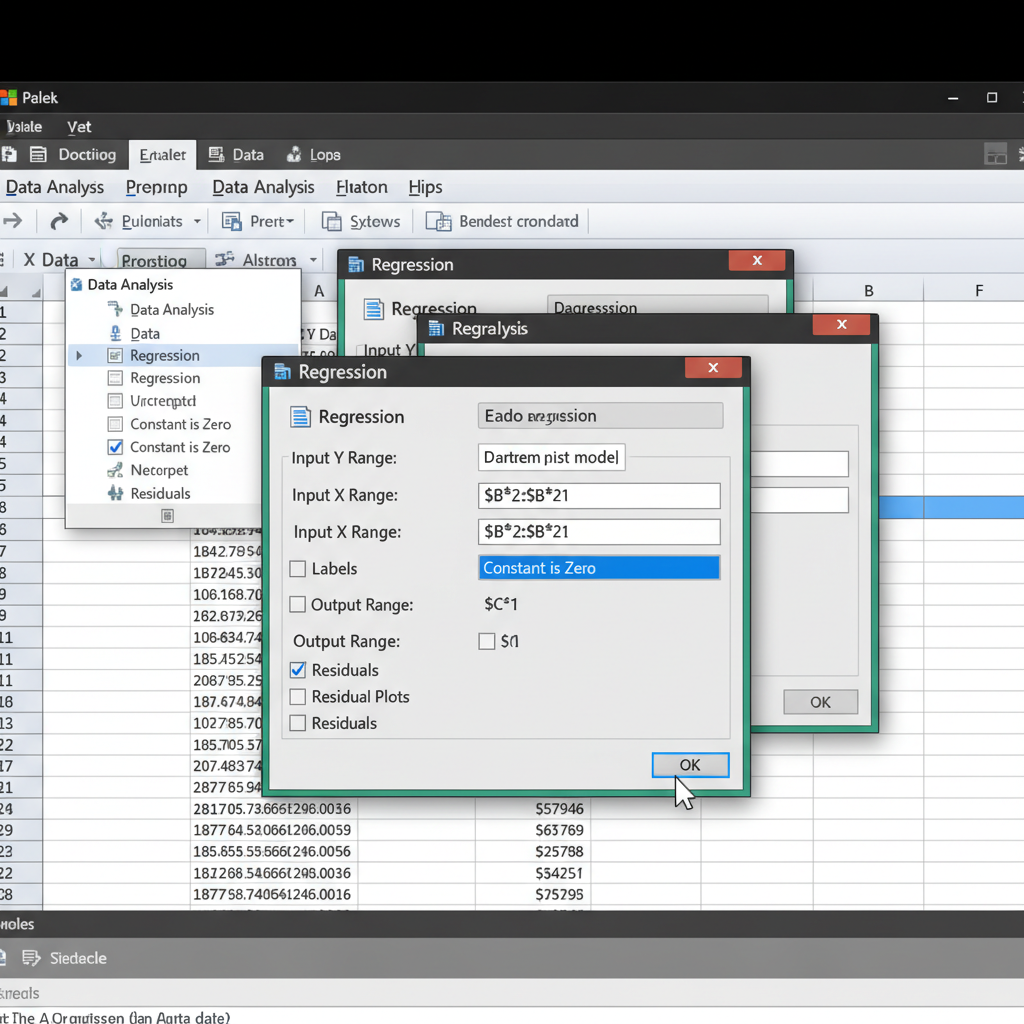
Navigate to the Data tab, click 'Data Analysis', and select 'Regression'. Run the tool twice: once with the 'Constant is Zero' checkbox selected, and once with it cleared.
Look at the summary output of both models and compare the 'Standard Error' and the 'Residual Sum of Squares' rather than relying strictly on the R-squared values.
When generating the regression output, check 'Residual Plots'. Ensure that the errors are randomly distributed across the horizontal axis and do not show an obvious pattern.
Test with Anonymized Sample Data
Create a controlled test environment to verify your regression results and reproduce the calculation differences safely.
Perform Accurate Linear Regression with WPS Spreadsheet
WPS Spreadsheet provides robust statistical functions and charting tools, enabling you to accurately calculate and visualize regression models with or without a zero intercept.
- 1. Insert a scatter chart: Open your dataset in WPS Spreadsheet, highlight your data points, go to the 'Insert' tab, and select 'Scatter Chart'.
- 2. Add a trendline: Click on a data point in the chart, choose 'Add Trendline' from the menu, and select a linear trendline.
- 3. Display R-squared: In the trendline options panel, check the box for 'Display R-squared value on chart'.
- 4. Set the intercept to zero: To force the regression through the origin, check 'Set Intercept' in the same panel and enter 0, then observe how the R-squared value recalculates.

Frequently Asked Questions
Why exactly does the R-squared formula change when the intercept is zero?
In a standard linear regression, R-squared measures the proportion of variance explained relative to the mean of the dependent variable. In a zero-intercept model, it measures variance relative to an absolute zero. This shifts the denominator of the equation, making direct comparisons of R-squared between the two models mathematically invalid.
Can I use formulas instead of the Data Analysis Toolpak to set a zero intercept?
Yes. You can use the LINEST function. Set the third argument (const) to FALSE (e.g., =LINEST(Y_range, X_range, FALSE, TRUE)). This explicitly tells the application to calculate the regression line without an intercept.
How do I know if my regression line should pass through the origin?
You should only set the intercept to zero if your underlying theory demands it. For example, in a physics experiment where zero input must strictly yield zero output (like distance traveled at zero speed). If there is no such theoretical constraint, use the default regression with an intercept.
What is the best metric to evaluate a zero-intercept model if R-squared is flawed?
Instead of relying on R-squared, use the Standard Error of the regression or compare the Residual Sum of Squares (RSS). Lower residual values and smaller standard errors generally indicate a better fit for your data.


