

Calculate Loan Payments After a 90-Day Same-as-Cash Period in Excel

Question details
The user needs an Excel formula to calculate the monthly payments for a loan featuring a 90-day same-as-cash deferral where interest accrues and is added to the principal.
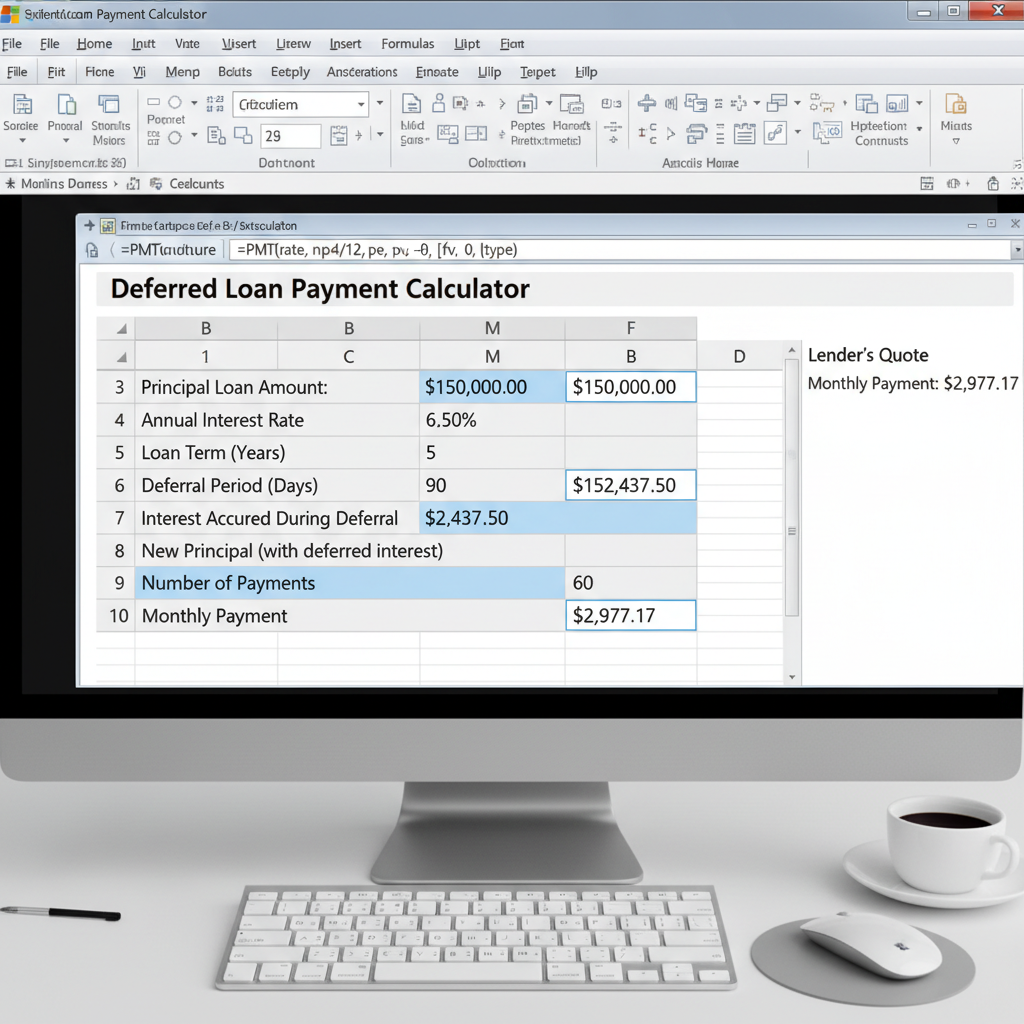
- Product
- Excel
- Device & OS
- not provided
- Scenario
- Building a financial worksheet to bypass a proprietary lender application for a simple-interest loan with deferred payments.
- Observed behavior
- The lender's application provides exact payment amounts. Replicating this requires adding the 90-day accrued interest to the principal and carefully adjusting the PMT function arguments for payment timing and exact day counts.
Gather your exact loan terms, including the original principal, annual interest rate, exact deferral period (90 days vs. 3 full months), and whether payments are due at the beginning or end of each period.
Use the PMT Function with Accrued Principal
Calculate the new financed balance by adding the 90-day simple interest to the original loan amount, then use the PMT function to find the monthly payment.
When a loan has a 'same-as-cash' period but isn't paid off during that window, interest generally accrues from day one. To find your actual monthly payment for the repayment term, you must first calculate the accrued interest and add it to your starting principal.
Differences of a few cents between your formula and a lender's application usually come down to how they count the deferral period (exactly 90 days vs. 3 whole months) and payment timing (beginning vs. end of the month).
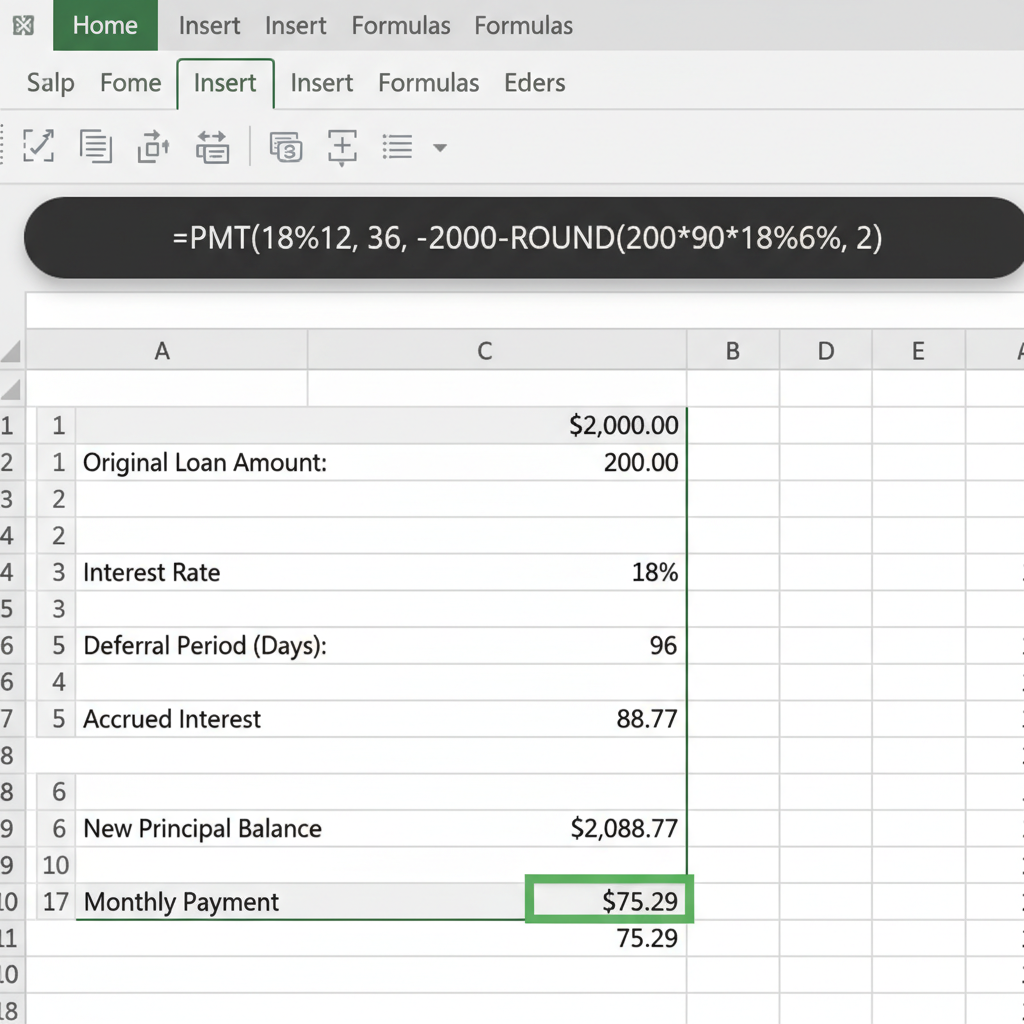
Determine the interest for the 90-day period. For a $2,000 loan at 18%, calculate the daily interest and multiply by 90 using the formula: ROUND(2000*90*18%/365, 2).
Select an empty cell and type =PMT(. The PMT function requires the rate, number of periods (nper), and present value (pv).
For the rate argument, enter 18%/12 to get the monthly interest. For the periods, enter your payment term (e.g., 12, 24, or 36). If the 90 days eat into a 36-month term, use 3*12-3. If the term starts after the 90 days, use the full term length.
Enter =PMT(18%/12, 36, -2000-ROUND(2000*90*18%/365, 2)) to get the final monthly payment. Note the negative sign before the principal, which ensures the payment outputs as a positive number.
Calculate Complex Loan Amortizations Effortlessly with WPS Spreadsheet
WPS Office Spreadsheet provides full support for advanced financial functions like PMT, PPMT, and IPMT. You can easily build amortization tables, calculate deferred interest, and format your financial data exactly like Microsoft Excel.
- 1. Open WPS Spreadsheet: Launch WPS Office and create a new blank spreadsheet or open your existing loan tracker.
- 2. Insert the PMT Function: Click on the 'Formulas' tab, select 'Financial', and choose 'PMT' from the drop-down menu.
- 3. Fill in the Arguments: Use the pop-up dialogue box to input your monthly rate, number of periods, and your adjusted present value (principal + 90-day interest).
- 4. Save as Excel Format: Go to Menu > Save As, and choose the .xlsx format to ensure your financial models remain fully compatible.

Frequently Asked Questions
Why does my calculated loan payment differ slightly from the lender's document?
Lenders may use different rounding rules, base their year on 360 days instead of 365, or calculate the deferral period as 3 exact months rather than 90 days. Payment timing (beginning vs. end of the month) also shifts the final penny amounts.
How do I calculate interest for exactly 3 months instead of 90 days?
Instead of multiplying the principal by 90/365, you can calculate the interest based on monthly compounding or simple interest per month. For example, simply add 3 months of interest by taking the monthly rate (18%/12) multiplied by 3, then multiplying by the principal.
What does the 'type' argument in the PMT function do?
The 'type' argument indicates when payments are due. Omit it or enter '0' if payments are due at the end of the payment period. Enter '1' if payments are due at the beginning of the period.
Can I build an amortization schedule for a loan with a same-as-cash period?
Yes. Start your amortization table with the principal balance equal to the original loan plus the accrued interest from the same-as-cash period. Then, use the PMT, IPMT (Interest Payment), and PPMT (Principal Payment) functions to map out each subsequent month's payment.


