



How to Calculate Loan Interest with Delayed and Partial Payments in Excel

Question details
The user needs to calculate half-yearly loan interest on a principal of 1,000,000 rupees at 13% annually, factoring in delayed partial payments made after the first interest due date.
- Product
- Excel
- Device & OS
- not provided
- Scenario
- Calculating accrued interest and updating principal balances when loan payments are irregular, delayed, or made in partial amounts.
- Observed behavior
- Standard loan calculations fail to account for irregular part-payments and improperly treat unpaid interest without confirming capitalization rules.
Before calculating, review your loan agreement to confirm the specific rules for payment allocation (e.g., whether payments apply to interest first or principal) and unpaid interest capitalization.
Set Up an Amortization Table for Irregular Payments
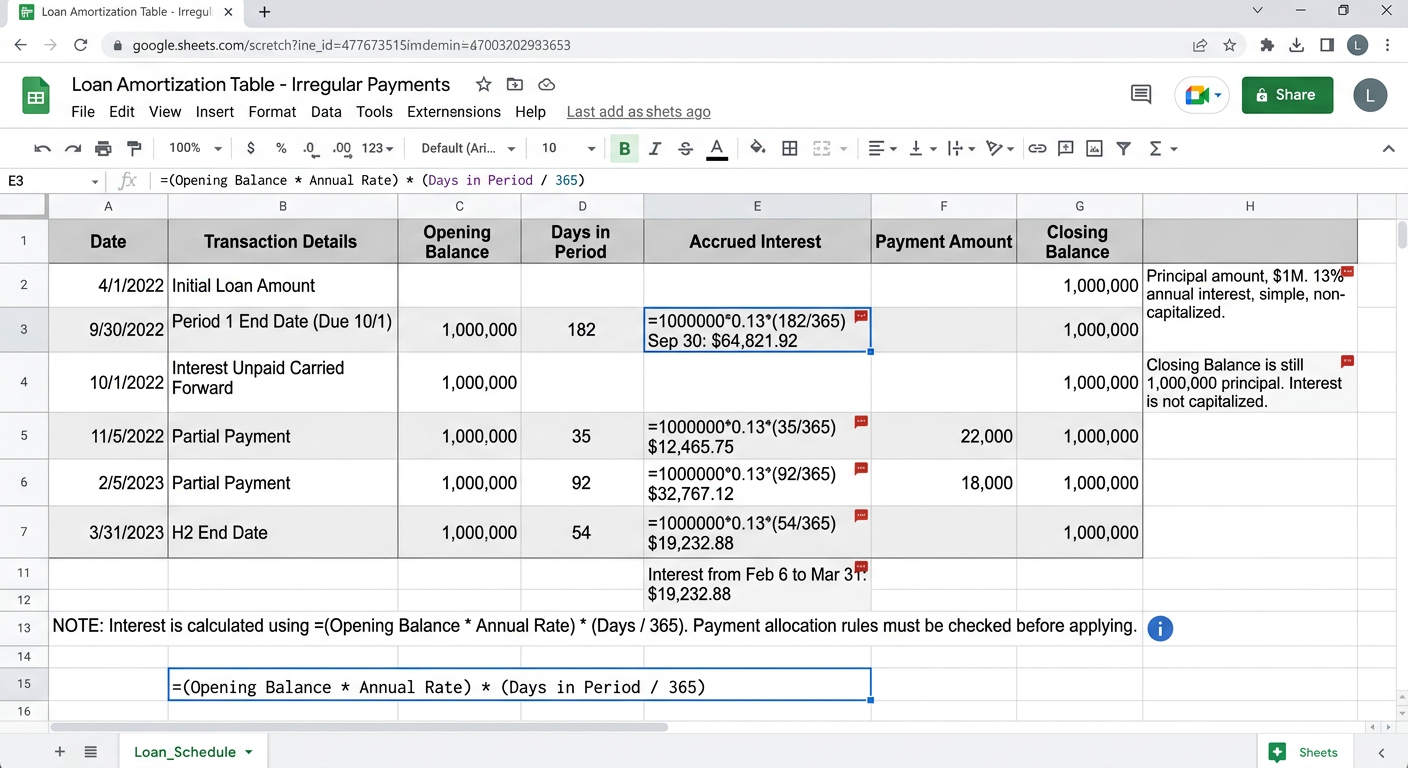
Use a spreadsheet table to track opening balances, accrued interest, partial payments, and closing balances for each specific date interval.
When payments are delayed or partial, standard fixed-period formulas (like PMT) will not work accurately. You must calculate the interest based on the exact number of days between each transaction.
Ensure you calculate the exact days for the periods between the start date, the first due date, and the specific dates the partial payments were made (e.g., November 5 and February 5).
In your spreadsheet, create columns for: Date, Transaction Details, Opening Balance, Days in Period, Accrued Interest, Payment Amount, and Closing Balance.
Input the starting date (e.g., April 1, 2022) and set the initial loan amount (1,000,000) as the Opening Balance.
For the first period ending September 30, calculate the accrued interest using the formula: =(Opening Balance * 13%) * (Days in Period / 365). Record the unpaid accrued interest.
Add a row for November 5. Calculate the interest accrued from October 1 to November 5. Subtract the 22,000 partial payment from the balance based on your agreement's allocation rules (usually covering interest first).
Add another row for the February 5 payment of 18,000. Calculate interest from November 6 to February 5, apply the payment, and then calculate the final balance through the end of the half-year (March 31, 2023).
Calculate Complex Loan Schedules with WPS Spreadsheet
WPS Spreadsheet provides all the financial formulas, date calculation functions, and formatting tools needed to track irregular loan payments, interest capitalization, and closing balances with ease.
- 1. Open a blank workbook: Launch WPS Spreadsheet and create a new blank workbook to set up your financial tracking.
- 2. Set up your headers: Create columns for Date, Opening Balance, Interest, Payment, and Closing Balance to organize your data.
- 3. Use date functions: Use the DAYS() function to automatically calculate the exact number of days between partial payment dates.
- 4. Save as .xlsx: Save your document in the standard .xlsx format to ensure seamless sharing with financial institutions or accountants.
Frequently Asked Questions
Does a partial payment reduce the principal or the accrued interest first?
This depends entirely on your specific loan agreement. Generally, partial payments are allocated to cover accrued interest first, and any remaining amount is then applied to reduce the principal balance.
How do I calculate interest for a specific number of days in a spreadsheet?
You can calculate daily interest by multiplying the principal balance by the annual interest rate, then dividing by 365 (or 360, depending on banking rules). Multiply that daily rate by the number of days between payments: =(Principal * Rate / 365) * Days.
What does it mean to capitalize unpaid interest?
Capitalizing interest means taking the unpaid accrued interest and adding it to the main principal loan amount. Future interest is then calculated on this new, higher principal balance, resulting in compound interest.


