

How to Calculate an Excel Loan with an Irregular First Payment Period

Question details
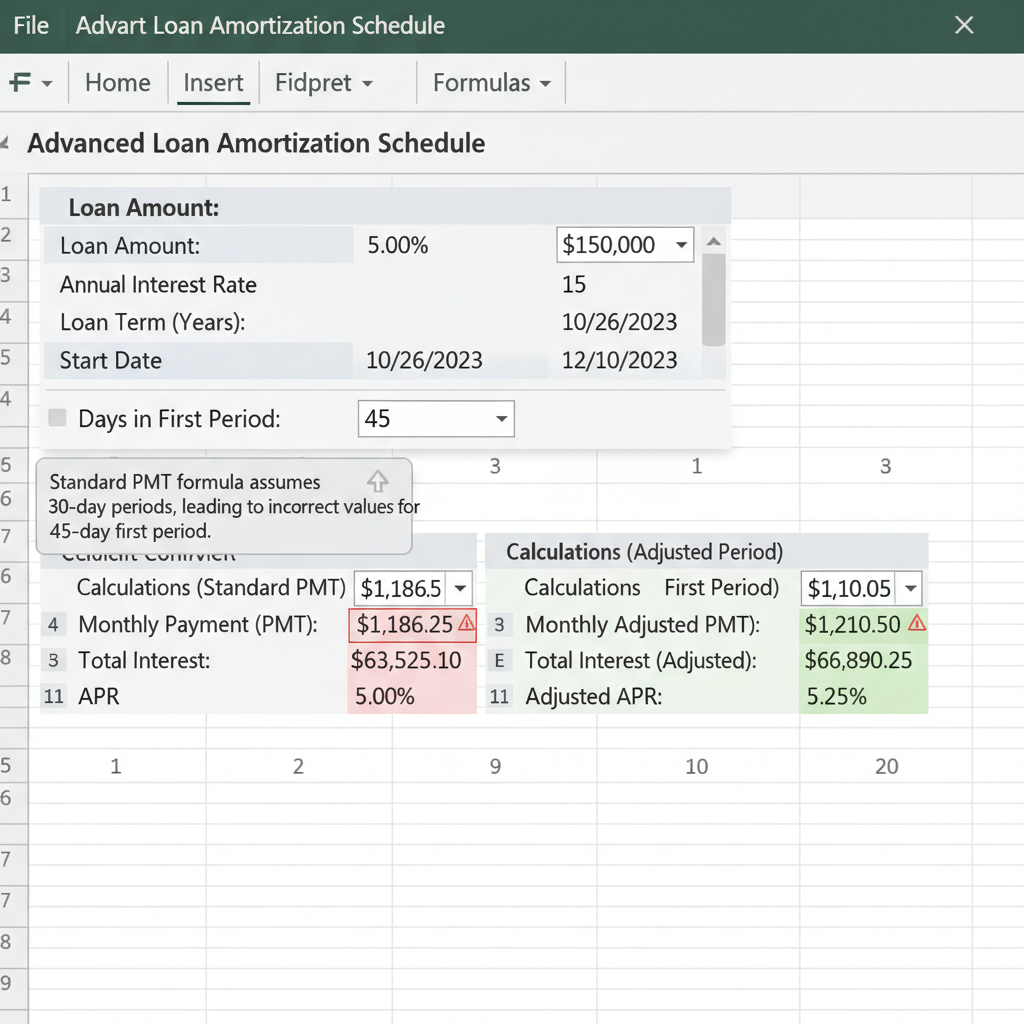
The user needs to accurately calculate the loan payment, interest, and APR when the first payment period is longer than a standard month (e.g., 45 days instead of 30 days).
- Product
- Excel
- Device & OS
- not provided
- Scenario
- Building or adjusting a loan amortization calculator where the start date and the first payment date do not follow a standard 30-day interval.
- Observed behavior
- Standard PMT calculations produce incorrect payment amounts, interest accruals, and APR values because they assume regular 30-day periods and cannot handle an extended 45-day first period.
Verify your lender's specific day-count convention (such as Actual/360 or Actual/365), as this significantly impacts how daily interest is accrued during the extended first period.
Use Cash Flow Modeling and Goal Seek to Find the Payment
Model the exact payment dates line-by-line and use Excel's Goal Seek tool to determine the correct payment amount.
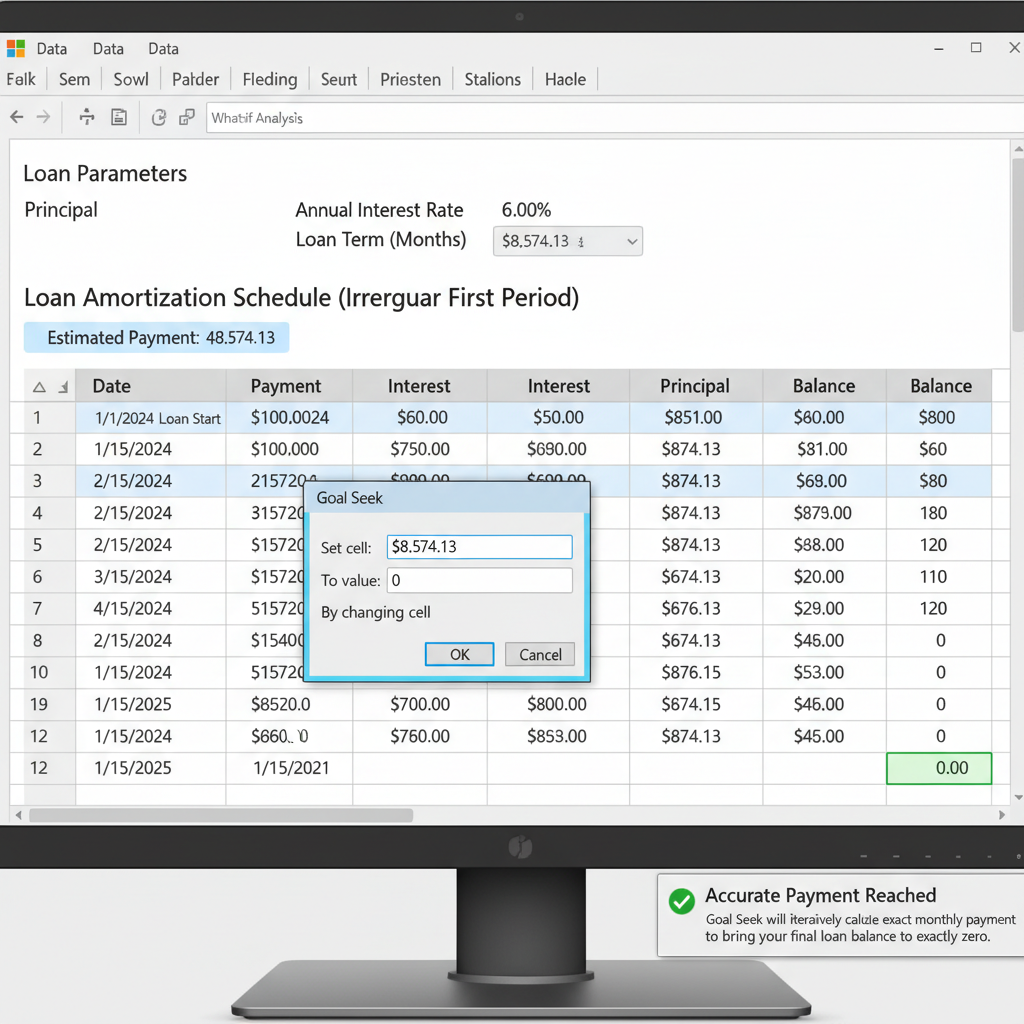
Standard PMT functions only work for equal payment intervals. For an irregular first period, you must model the loan schedule based on actual calendar dates and use What-If Analysis to find the payment amount that perfectly pays off the loan.
Set up columns for Date, Payment, Interest, Principal, and Balance. Enter your loan start date in the first row and the actual payment dates for the remaining rows.
For the first period's interest cell, calculate the exact days between the start date and first payment date. Multiply the daily interest rate by this number of days, and then by the starting loan balance.
Create a separate cell designated as 'Estimated Payment' (leave it blank or enter an estimate for now). Link the Payment column in your table to this reference cell.
Navigate to Data > What-If Analysis > Goal Seek. Set the final period's Balance cell to 0 by changing the 'Estimated Payment' cell, then click OK.
Calculate the Accurate APR Using the XIRR Function
Use the XIRR function to find the true Annual Percentage Rate (APR) based on irregular cash flow dates.
Easily Calculate Complex Loans in WPS Spreadsheets
WPS Spreadsheets provides full support for advanced financial functions like XIRR, XNPV, and Goal Seek, allowing you to accurately model loans with irregular payment periods.
- 1. Open a Blank Spreadsheet: Launch WPS Spreadsheets and create your loan amortization table using exact payment dates.
- 2. Use the XIRR Function: Input =XIRR() to calculate the precise APR based on your exact cash flow dates, ensuring full compatibility with standard Excel models.
- 3. Utilize Goal Seek: Navigate to the Data tab, click What-If Analysis, and select Goal Seek to find the exact payment amount that clears the loan balance.

Frequently Asked Questions
Why doesn't the PMT function work for irregular first periods?
The PMT function inherently assumes that all payment periods are exactly equal in length (e.g., exactly one month apart). When a period is longer or shorter, the interest accrual is different, requiring an actual cash-flow calculation based on exact days instead.
How do I calculate daily interest for the extra 15 days in an extended period?
Divide your annual interest rate by the lender's year basis (typically 360 or 365 days) to find the daily rate. Multiply this daily rate by the loan balance, and then multiply the result by the exact number of days (e.g., 45 days) to find the total interest for that period.
What is the difference between IRR and XIRR for loan calculations?
IRR assumes that all cash flows occur at perfectly regular intervals. XIRR allows you to assign specific calendar dates to each cash flow, making it the correct and accurate function to use when your loan has irregular payment dates.


