

How to Calculate a Loan with a 45-Day First Payment in Excel

Question details
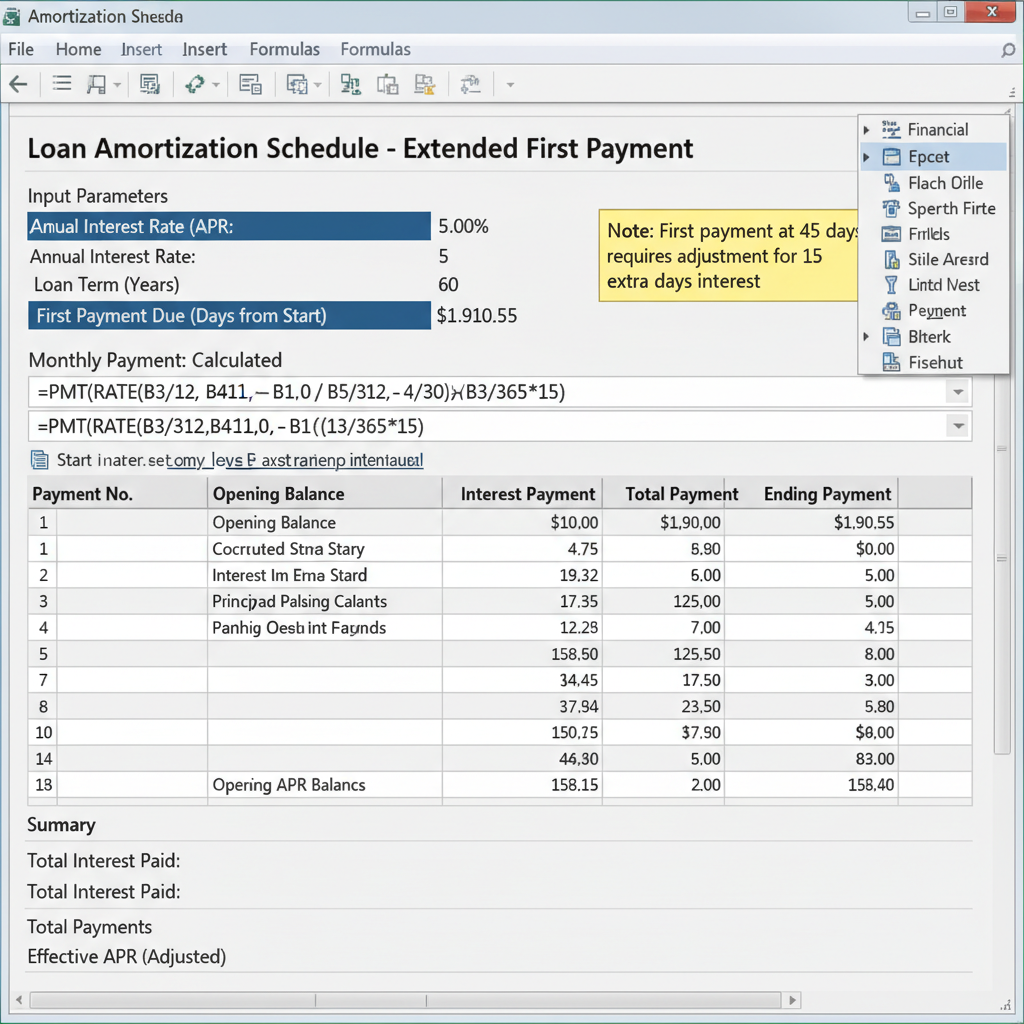
The user needs to calculate a loan schedule where the first payment occurs 45 days after the loan start date instead of the standard 30 days.
- Product
- Excel
- Device & OS
- not provided
- Scenario
- Building a loan amortization or financial model in Excel that accounts for an extended 45-day first payment period.
- Observed behavior
- Standard Excel PMT functions assume regular intervals, requiring a manual adjustment to account for the extra 15 days of interest, which affects the financed amount, APR, and total interest.
Ensure you have the loan principal amount, annual interest rate, loan term, loan start date, and the exact first payment date ready in your spreadsheet.
Adjust the Initial Loan Balance for the Extra Days
Calculate the daily interest rate to find the interest accrued during the extra 15 days, then add this to the principal before calculating the regular payments.
Because standard financial functions like PMT assume evenly spaced periods, an extended first payment period requires you to manually capitalize the extra interest into the starting loan balance.
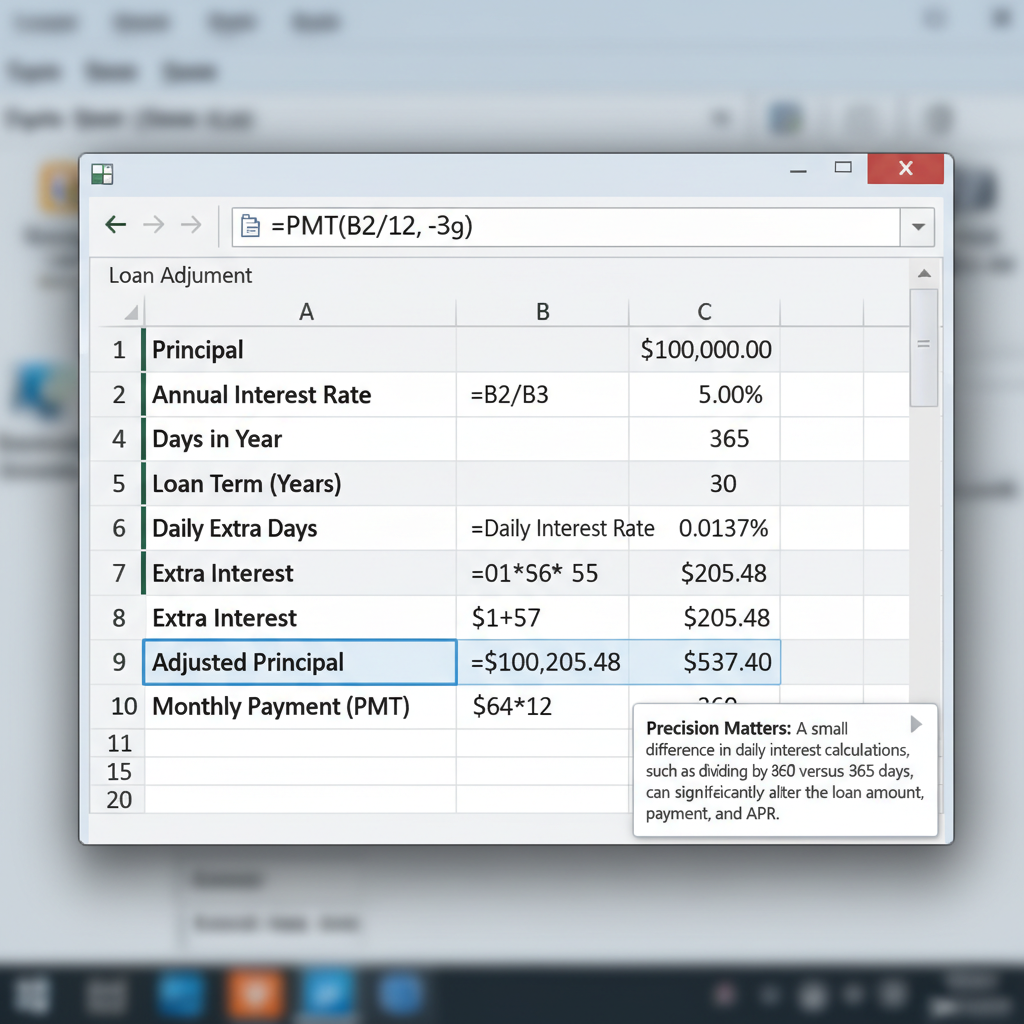
In your Excel sheet, enter the Principal, Annual Interest Rate, Days in Year (e.g., 365), and Loan Term in separate cells.
Divide the Annual Interest Rate by the number of days in the year (e.g., =B2/365) to find the daily rate.
Multiply the initial loan amount by the daily interest rate, then multiply by the 15 extra days (e.g., =Principal * Daily_Rate * 15).
Add the extra interest to the initial principal amount to get the new total financed amount.
Use the Excel PMT function (e.g., =PMT(Annual_Rate/12, Total_Months, -Adjusted_Principal)) to find the correct regular payment amount.
Build a Custom Amortization Schedule Using Exact Dates
Create a row-by-row amortization table that calculates interest based on the exact number of days between payment dates.
Easily Calculate Complex Loans in WPS Spreadsheet
WPS Spreadsheet provides powerful financial functions like PMT, IPMT, and exact date calculations, making it simple to model loans with irregular payment periods like a 45-day first payment.
- 1. Open WPS Spreadsheet: Launch WPS Office and open a new or existing spreadsheet to build your loan model.
- 2. Input Loan Variables: Enter your initial loan amount, annual interest rate, and specific dates including the 45-day first payment date.
- 3. Apply Financial Formulas: Use standard financial formulas like PMT or custom daily interest formulas just as you would in Excel.
- 4. Save and Export: Save your work seamlessly in .xlsx format to ensure complete compatibility with other spreadsheet software.

Frequently Asked Questions
Why does a 45-day first payment change my loan amount?
Most standard loan calculations assume the first payment is made exactly one period (usually 30 days) after the loan starts. An extra 15 days means interest accrues for a longer time before the first payment reduces the principal, effectively increasing the total financed amount if that interest is rolled into the loan.
Which Excel function is best for irregular payment dates?
While the standard PMT function works for regular intervals, XIRR and XNPV functions are better suited for cash flows with irregular dates. However, for a simple irregular first payment, manually adjusting the starting principal for the extra days before using PMT is usually the easiest method.
Should I use 360 or 365 days to calculate daily interest?
This depends on the terms of your loan agreement. Many commercial loans use a 360-day year (Actual/360 method) which slightly increases the interest paid, while consumer loans often use a 365-day year. Always check your loan contract for the exact day-count convention.


